Home / Finance Center / First-Time Car Buyer
First-Time Car Buyer Guide: Getting Your First Car Loan in North Hampton, NH
Buying your first car? You can apply to finance it with us, even with little or no credit history. This guide covers how a car loan works, what lenders look at, and what to bring so the day goes quickly.
We're McFarland Hyundai, 177 Lafayette Rd on Route 1 in North Hampton. First-time buyers from Hampton, Portsmouth, Exeter, Rye, Stratham and Seabrook come here for one reason. They want someone to explain the deal before they sign it. We take your application to the lenders and walk you through every option that comes back.
How a car loan works
A car loan is money a lender gives you to buy the car. You pay it back monthly over a set number of months. Five terms decide what it costs you.
Principal.
This is the amount you borrow and agree to pay back. Your down payment and trade-in lower it.
Interest rate and APR.
The interest rate is the yearly cost of borrowing, shown as a percentage. The APR adds the loan's fees to that, so it's the better number to compare. Federal law requires the lender to show you the APR before you're bound by the loan.
Term.
This is how long the loan runs, usually counted in months. A longer term can lower the monthly payment, but you pay more interest over the life of the loan. A shorter term lowers your total cost.
Monthly payment.
Each payment covers some interest and pays down some principal.
Total cost.
This is everything you pay for the car over the life of the loan: principal, interest, and any down payment or trade-in.
A longer loan also raises the risk of negative equity, which means you owe more than the car is worth. That matters when you trade it in later.
We don't quote rates on this page. Your rate comes from the lender after it reviews your application, and it depends on your credit. When it comes back, we show it to you and explain it.
Credit basics for first-time buyers
Lenders use your credit report and credit score to decide whether to lend and at what rate. Here's what those words mean.
What's a credit score?
A credit score is a three-digit number that predicts how likely you are to pay a loan back on time. It's built from the information in your credit reports.
300 to 850
Base FICO Scores
250 to 900
FICO Auto Scores
FICO is the best-known brand. Base FICO Scores run from 300 to 850. FICO looks at five things: whether you pay on time, how much you owe, how long you've had credit, how often you apply for new credit, and the mix of credit you have. Payment history carries the most weight.
You have more than one score. Each one depends on the scoring model, the bureau's data and the day it's calculated. VantageScore is another scoring brand that lenders can use.
Car loans add one more twist. Many auto lenders use FICO Auto Scores, which are built for car loans and run from 250 to 900. Each lender picks which score it uses and what else it looks at. So a score you check yourself may differ from the one a car lender pulls.
The three credit bureaus
Three nationwide credit bureaus keep credit reports: Equifax, Experian and TransUnion. Your scores come from the data in those reports.
Equifax
Experian
TransUnion
You can get your reports from all three for free, once a week, at AnnualCreditReport.com. That's the only site federal law authorizes for free reports. Checking your own reports there doesn't affect your credit scores.
Pull your reports before you shop. Look for accounts you don't recognize and mistakes. You can dispute inaccurate information for free.
No credit vs bad credit
No credit and bad credit are different problems.
No credit, or a thin file, means you don't have enough credit history to produce a score. Lenders simply have little to go on. That's where a lot of first-time buyers start, and our finance team works with buyers in that spot.
Bad credit means your report shows problems like late payments or collections. If that's part of your picture, our second chance financing page covers it.
Soft vs hard inquiries
Every time someone looks at your credit, it's an inquiry. There are two kinds.
Soft inquiries include checking your own credit and prescreening by lenders. They don't affect your credit scores, and other lenders can't see them.
Hard inquiries happen when you apply for credit and a lender reviews your report to decide on the loan. They can affect your score, because most scoring models look at how often and how recently you apply.
For most people, one hard inquiry takes less than five points off a FICO Score. Inquiries can count for more when you have few accounts or a short history. Hard inquiries stay on your report for up to two years, but FICO Scores only count them for one year.
Shopping for a loan without stacking inquiries
Comparing loans is smart. FICO accounts for it. FICO Scores group multiple auto loan inquiries made within a short window into one inquiry. That window is 14 days on older FICO versions and 45 days on newer ones. The CFPB gives the same advice: keep your loan shopping inside 14 to 45 days.
A dealer may send your application to several lenders. Keep your car shopping to a few weeks so those inquiries land inside the window.
How to get approved with little or no credit
Lenders want to see that you can make the payment and will. With no credit history, they look harder at the rest of your file. Here's what helps.
Proof of income.
Pay stubs show the lender you have money coming in every month.
Proof of residence.
A utility bill or lease with your name and address shows stability.
A down payment.
A down payment can help, but how much you need depends on the lender and your situation. Putting more down means you borrow less, and it may lower your monthly payment and total cost.
A co-signer.
A co-signer is a parent, relative or friend who signs the loan with you. If your credit history is limited, a co-signer with good credit could lower your interest rate, because the lender uses their credit too. It's a real obligation. A co-signer has to pay the loan if you don't, and late payments show up on both credit reports. In general, a lender can't require a co-signer unless you apply for joint credit.
Then make every payment on time. Payment history is the biggest factor in a FICO Score, so an on-time car payment every month can help you build credit. Missed payments bring late fees, possible repossession and negative entries on your credit report.
We'll tell you plainly what the lenders say. Whether a lender approves the loan depends on your income, your down payment and the car you choose.
For more detail, read our guide to first-time car buyer loans.
New vs used for your first car
Start with how you'll use the car. A daily drive up Route 1 to work or class? Weekend trips? Do you want AWD for New Hampshire winters, or is a sedan enough? Then look at the tradeoffs.
New Hyundai
A new Hyundai comes with Hyundai's factory warranty, America's Best Warranty. Every new Hyundai you finance at McFarland Hyundai also comes with the McFarland Protection Package, free, for 1 year from the date of sale. New Elantra, Kona and Venue models may also qualify for the Hyundai First-Time Buyer program, covered below. Browse new inventory.
Used car
A used car can cost less up front, which can mean a smaller loan. Budget for wear items like tires and brakes, which may come due sooner. Ask what coverage, if any, comes with the car you pick.
Every used car a dealer offers must carry an FTC Buyers Guide. It tells you whether the car comes with a warranty or is sold as is, and it becomes part of your sales contract. The FTC also suggests asking to have the car inspected by an independent mechanic before you buy. Browse used inventory.
Insurance and value
Get insurance quotes on the exact cars you're considering. Insurance for a first-time driver can be a big part of the monthly cost, and it changes with the car.
Cars also lose value over time. If you owe more than the car is worth, you have negative equity, and it has to be paid off when you trade in.
How much car can you afford?
Start with the monthly number, not the car. Pick a payment you can make every month without stretching. Then add what it costs to own the car.
The CFPB lists what moves your monthly and total cost:
- Interest rate and APR
- Fees on the deal
- Optional add-ons
- Insurance and maintenance
It also lists what brings the cost down: a bigger down payment, a less expensive car, and fewer add-ons.
Payment, insurance, gas and maintenance together are the real monthly cost of the car. Ask for the full out-the-door price before you sign.
If you have a car to trade, research its value before you come in. Trading it in or selling it yourself both lower the amount you borrow.
What to bring to the dealership
Lenders typically ask for:
- A valid driver's license.
- Proof of income, like recent pay stubs.
- Proof of residence, like a utility bill.
- Your insurance information. Lenders require insurance on the car you finance.
- The title or payoff information for your trade-in, if you have one.
Missing something? We'll tell you exactly what the lender needs.
Hyundai First-Time Buyer program
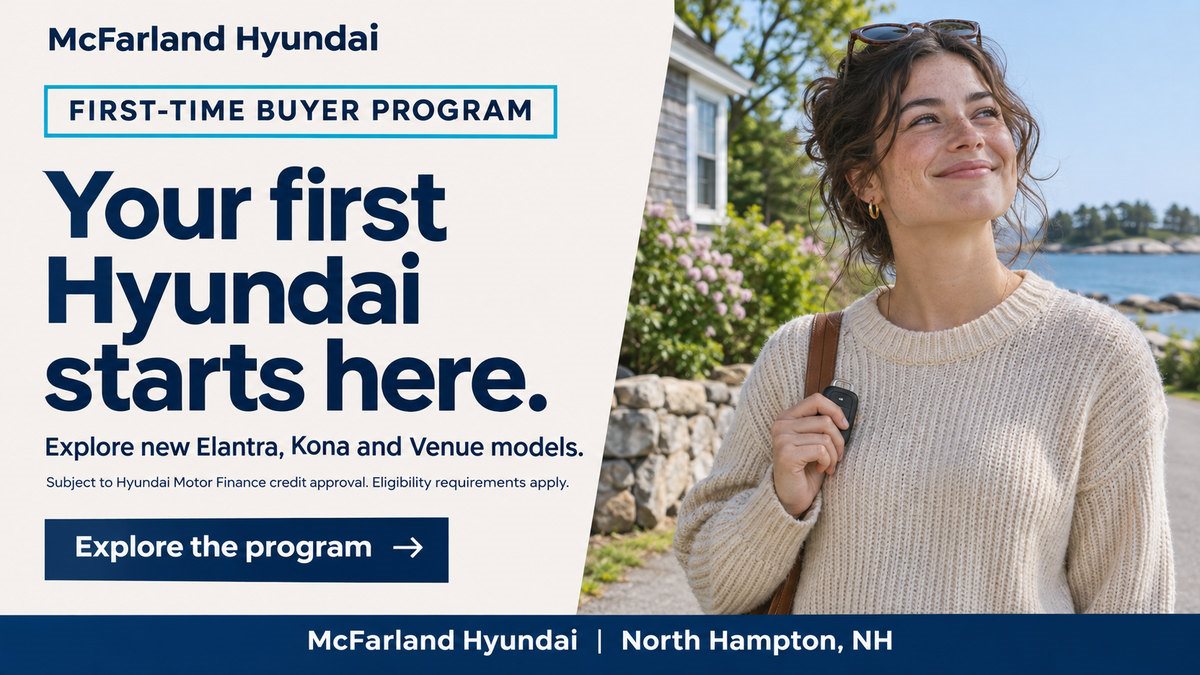
Hyundai Motor Finance has a First-Time Buyer program for buyers who have never had an auto loan. It runs November 17, 2026 through March 31, 2027.
It covers retail financing on new Hyundai Elantra, Kona and Venue models. It doesn't cover leases or used cars. Approved buyers may qualify for improved rate pricing, subject to credit approval by Hyundai Motor Finance.
To qualify, you need no previous auto loan on your credit file, no charge-offs and no derogatory credit in the last 12 months. Proof of income is required upfront.
Get the full details on our Hyundai First-Time Buyer program page.
Get pre-qualified or apply
You have two ways to start online.
Pre-qualifying at /pre-qual doesn't affect your credit score. It gives you a realistic budget before you shop.
Fill out the finance application.
This is a full credit application that goes to lenders. It isn't a soft pull.
Either one saves time when you come in. McFarland Hyundai has over thirty years of relationships with local and national banks and credit unions. Our finance team sends your application to the lenders that fit your situation.
Then you test drive the cars that fit, and we go over every lender response with you. Nothing gets signed until you understand it.
We're at 177 Lafayette Rd on Route 1 in North Hampton. Call ahead at (603) 697-7389 or send us a message so we can have the cars ready. Questions about loans in general? Visit our Finance Center.
First-time car buyer FAQ
Can I buy a car with no credit?
You can apply, and many first-time buyers do. No credit means a thin file, not bad credit. Lenders lean harder on your income, your down payment and the car you pick. We'll show you every option that comes back.
What credit score do I need to buy a car?
There's no single number. Each lender sets its own standards and picks which score it uses. In general, a higher score makes it easier to qualify and may get you a better rate. Pre-qualifying is a quick way to see where you stand.
Does pre-qualifying hurt my credit?
Not at /pre-qual. Pre-qualifying at /pre-qual doesn't affect your credit score. The full application at /getfinancing is different. It goes to lenders, and a lender's review when you apply for credit is a hard inquiry, which can affect your score.
Do I need a co-signer?
Not always. A lender generally can't require one unless you apply for joint credit. With a limited history, a co-signer with good credit could lower your rate. Your co-signer is on the hook for the loan if you miss payments, so talk it through first.
How much should I put down?
A down payment can help, but how much you need depends on the lender and your situation. The more you put down, the less you borrow, and that may lower your monthly payment and total cost.
Should my first car be new or used?
It depends on your budget and how you drive. A new Hyundai comes with Hyundai's factory warranty, America's Best Warranty. A used car can cost less up front. Tell us your monthly number and your commute, and we'll show you both.
How long does approval take?
It depends on the lender and how complete your paperwork is. Bring everything on the list above and fill out the application before you come in. That helps cut the wait.
Can I finance a car as a student?
You can apply. Lenders look at income, so a student needs proof of income like everyone else. If your income or history is thin, a down payment or a co-signer can help. If you're graduating soon or just finished school, see our college grad program page too.
I live in Massachusetts. How do taxes work?
If you finance, you can roll the Massachusetts tax into your loan or pay it when you register the car. That's your call. If you lease, the tax is built into the lease.
I live in Maine. How do taxes work?
If you finance, it works the same way: finance the tax or pay it when you register. If you lease, Maine charges 5.5% of your monthly lease payment. You can add that tax to the lease or pay it when you register.
Sources
- CFPB, Auto loans key terms
- CFPB, What should I know before I shop for a car or auto loan?
- CFPB, Take control of your auto loan (PDF)
- myFICO, What is a FICO Score?
- myFICO, FICO Score versions
- CFPB, What is a credit score?
- VantageScore
- AnnualCreditReport.com
- CFPB, How do I get a free copy of my credit reports?
- CFPB, What is a credit inquiry?
- myFICO, Credit checks and inquiries
- CFPB, Credit reports key terms (Thin credit file / No credit file)
- CFPB, Should I agree to co-sign someone else's car loan?
- FTC, Buying a Used Car (PDF via govinfo.gov)